BLOG


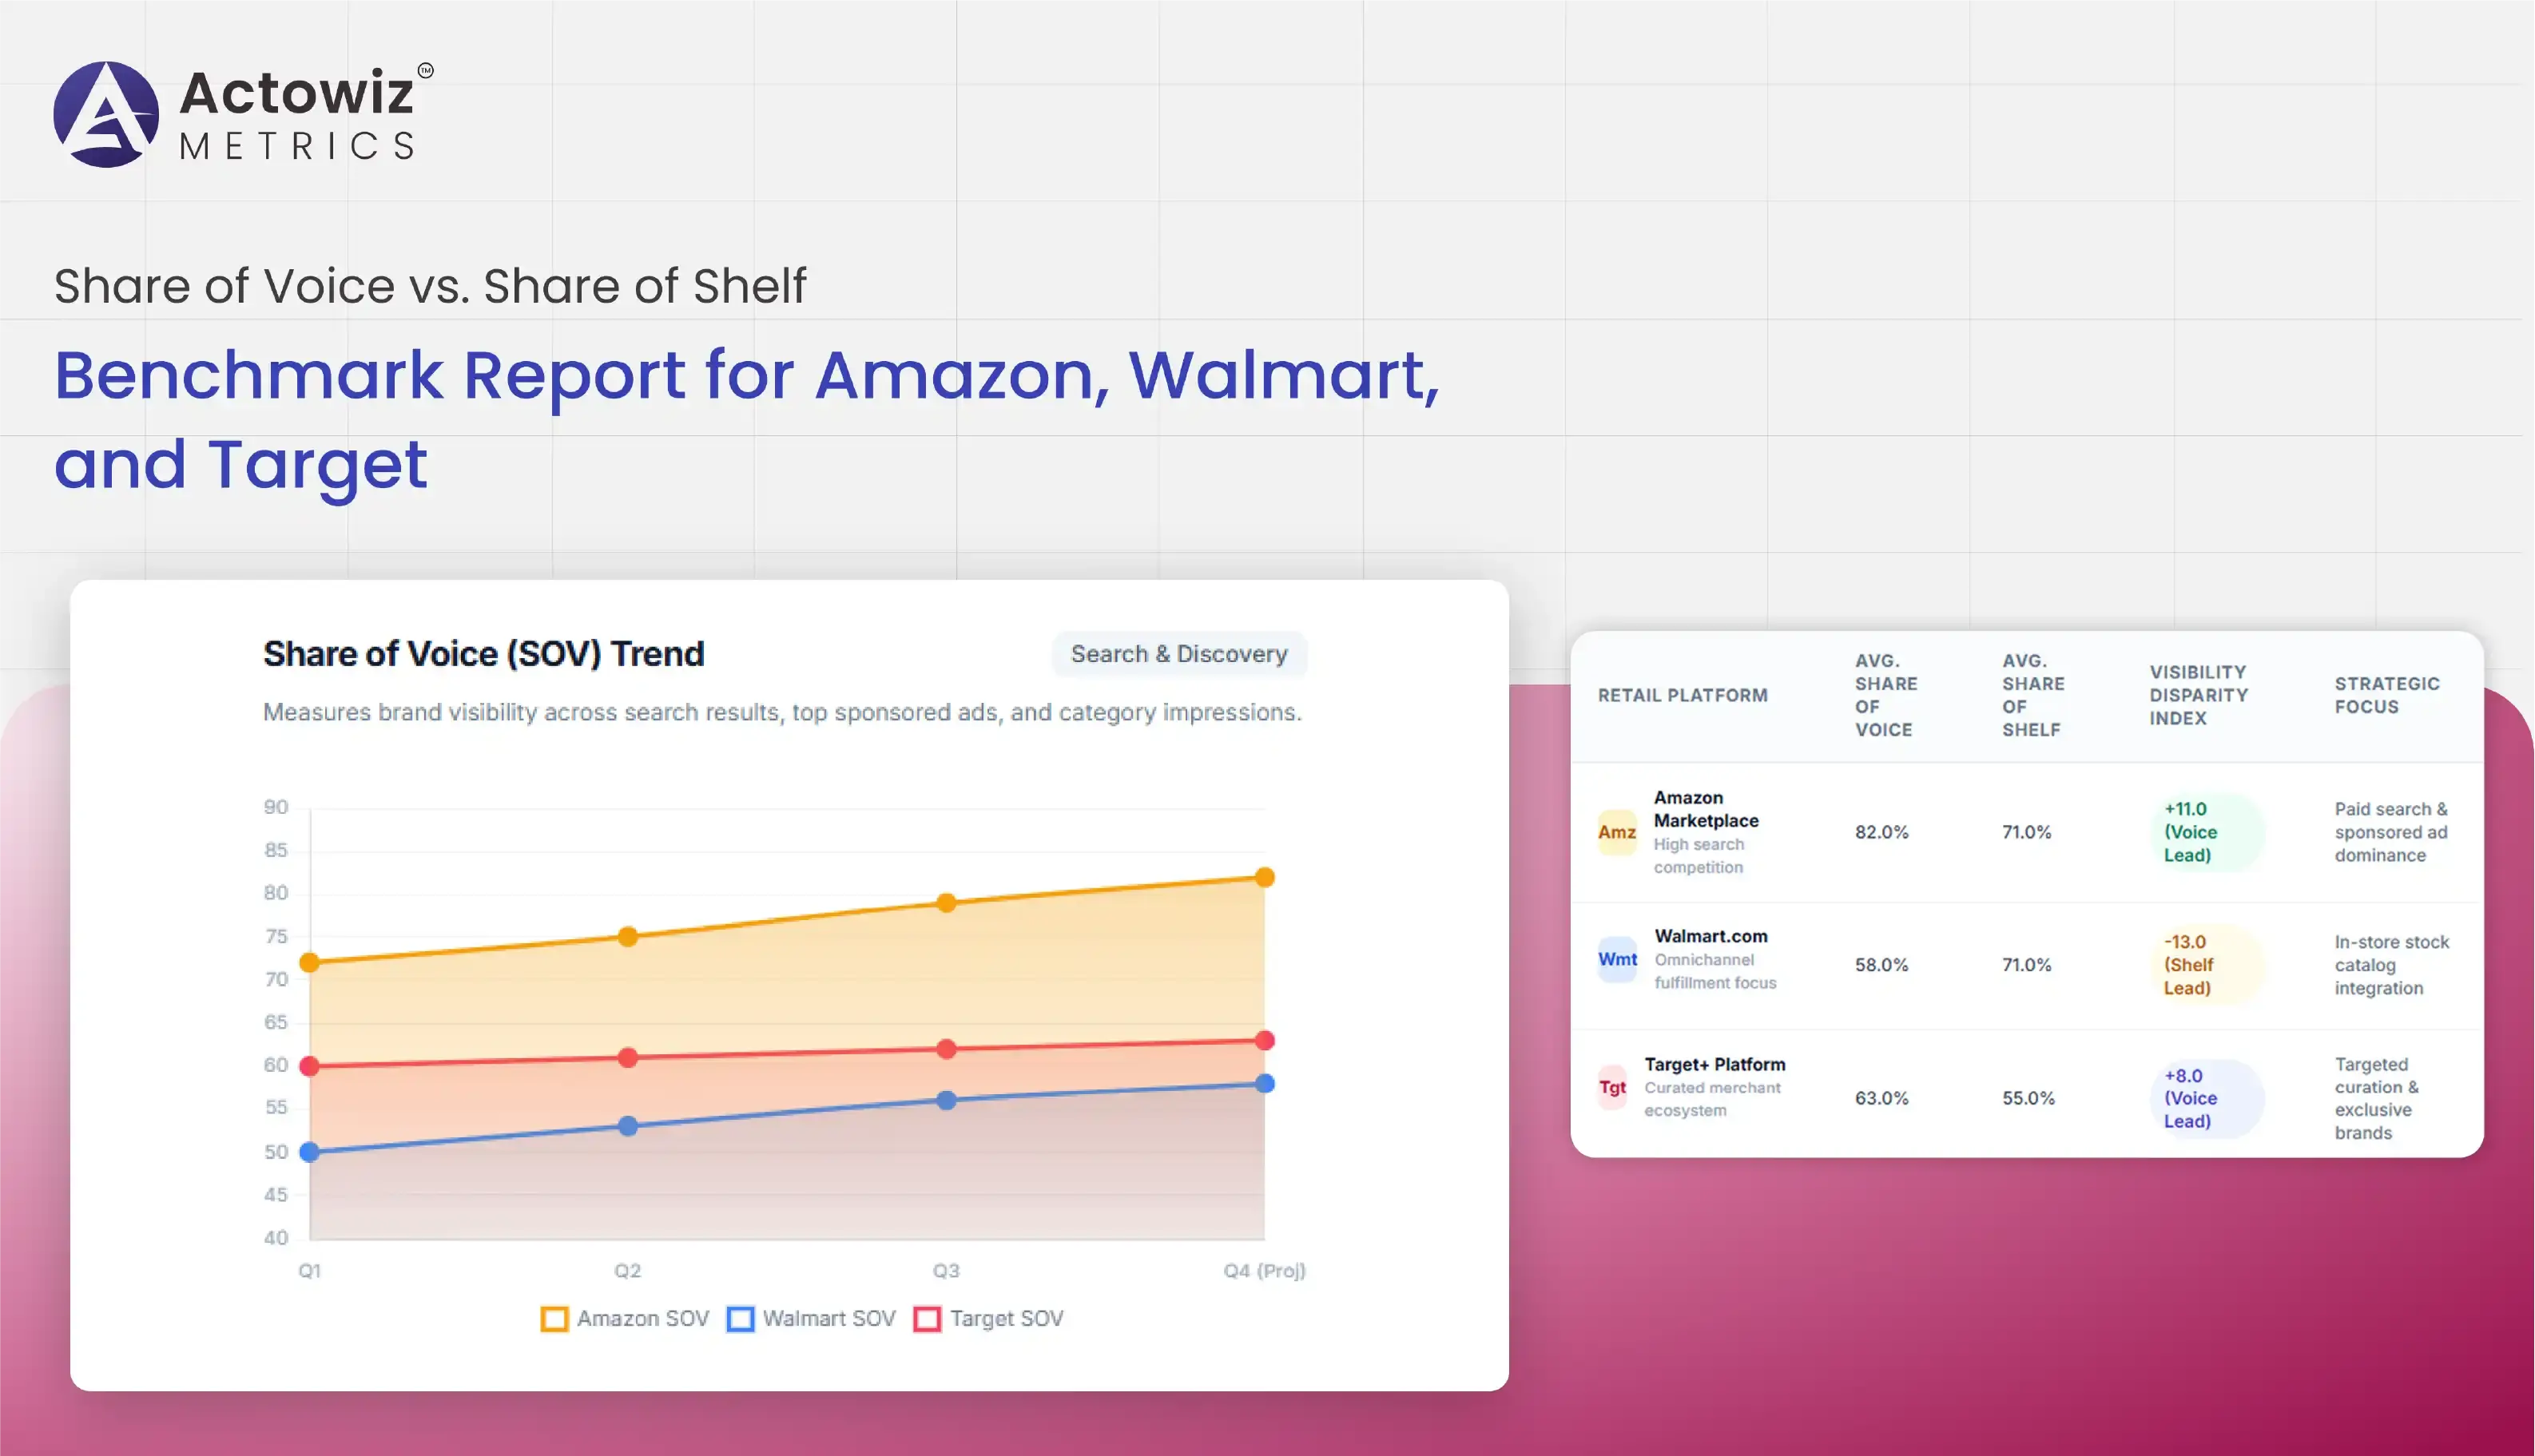
Digital retail has changed how brands compete for consumer attention. A product may have a strong assortment presence on a marketplace yet receive limited visibility in search results, category pages, sponsored placements, or other digital discovery environments. Conversely, a brand can generate significant online attention while maintaining relatively limited product representation across retail catalogs. Understanding this difference is essential for brands seeking to improve their digital retail performance.
The Share of Voice vs. Share of Shelf: Benchmark Report provides a framework for comparing digital visibility and product representation across major retail environments. The analysis focuses on Amazon, Walmart, and Target, three highly influential retail platforms where brands compete for search visibility, product placement, assortment coverage, and customer attention.
Amazon analytics can help brands evaluate product visibility, category presence, search performance, pricing, assortment, ratings, reviews, and competitor activity. Similar datasets can be developed for Walmart and Target to create a cross-retailer benchmarking framework.
From 2020 through 2026, e-commerce accelerated considerably, while consumers increasingly used retailer websites and marketplaces to discover products. This made digital shelf presence a critical component of brand strategy. Today, brands need to understand not only whether products are listed but also how prominently they appear relative to competitors.
This report examines the relationship between share of voice and share of shelf, explains how the two metrics can be benchmarked, and highlights how structured retail data can help brands identify visibility gaps and competitive opportunities.
The relationship between consumer attention and product availability has become increasingly important in digital commerce. Brands often assume that having a broad assortment automatically creates strong online visibility. However, product presence and consumer discoverability are different measurements.
Amazon share of voice and product visibility data collection enables brands to evaluate how frequently their products appear across relevant searches, categories, and competitive environments. When combined with assortment information, the resulting dataset can reveal whether a brand's digital presence matches its market ambitions.
| Year | Major Development | Benchmarking Focus |
|---|---|---|
| 2020 | E-commerce adoption accelerated | Product presence |
| 2021 | Marketplace competition increased | Search visibility |
| 2022 | Price competition intensified | Visibility versus pricing |
| 2023 | Retail media expanded | Sponsored and organic visibility |
| 2024 | Digital merchandising matured | Shelf and content quality |
| 2025 | AI-supported search increased | Search positioning |
| 2026 | Integrated retail intelligence expanded | Cross-platform benchmarking |
A brand with hundreds of products listed on Amazon may still have low share of voice if competitors dominate important searches. Conversely, a smaller assortment may generate strong visibility if those products consistently rank for high-value searches.
Data collection can monitor product titles, categories, prices, ratings, reviews, availability, search positions, sponsored placements, and competitor products. These fields can then be standardized to create comparable visibility metrics.
The 2020–2026 period illustrates how this distinction has become more important. Early digital commerce strategies focused primarily on getting products listed. As competition increased, brands began paying greater attention to search ranking, content quality, advertising, reviews, and digital merchandising.
Historical datasets allow businesses to track whether visibility improves after content updates, promotional campaigns, advertising investment, or assortment changes. This makes share-of-voice measurement more actionable than a one-time snapshot.
Walmart's extensive physical and digital retail footprint creates a significant environment for consumer brands. Product availability alone does not guarantee strong digital shelf representation. Brands must also understand how much space their products occupy compared with competing brands.
Walmart share of shelf analysis for consumer brands provides a way to evaluate assortment representation across categories and product segments.
| Year | Market Shift | Shelf Measurement Opportunity |
|---|---|---|
| 2020 | Digital grocery adoption increased | Online product presence |
| 2021 | Omnichannel retail expanded | Store and digital comparison |
| 2022 | Inflation changed category behavior | Price and assortment |
| 2023 | Private-label competition grew | Brand representation |
| 2024 | Digital merchandising improved | Content and placement |
| 2025 | Retail media gained importance | Visibility measurement |
| 2026 | Cross-channel intelligence matured | Integrated shelf benchmarking |
Share of shelf can be measured using the number of relevant SKUs, category representation, product positions, brand coverage, or other clearly defined indicators. For example, a consumer brand could compare the number of its products against the total products represented within a category.
However, digital shelf analysis should not rely solely on SKU counts. A brand with fewer products may occupy more valuable digital positions than a competitor with a larger catalog. Search ranking, featured placement, product content, ratings, and availability can therefore add context to the measurement.
Historical comparison can reveal whether a brand is expanding or losing digital representation. If competitors continually introduce products while a brand's assortment remains unchanged, its relative shelf presence may gradually decline.
By monitoring Walmart's digital environment consistently, brands can identify category gaps, competitor expansion, new product introductions, and changes in product availability.
Target represents another important digital retail environment where brands compete for customer attention. As consumers increasingly research products online before purchase, visibility across retailer search and category pages becomes strategically significant.
Target digital shelf share and competitor visibility monitoring can help brands evaluate how prominently products are represented and how that representation changes over time.
| Year | Digital Retail Development | Key Measurement |
|---|---|---|
| 2020 | Online shopping increased sharply | Product discoverability |
| 2021 | Digital assortment expanded | Category coverage |
| 2022 | Value became increasingly important | Pricing and promotions |
| 2023 | Search became more competitive | Ranking and visibility |
| 2024 | Retail media expanded | Paid visibility |
| 2025 | Data automation improved | Recurring monitoring |
| 2026 | Cross-platform comparison matured | Competitive visibility |
Brands can monitor the frequency with which products appear for relevant keywords and categories. They can also compare the number of competing products displayed around those results.
This creates a useful distinction between presence and prominence. A product can technically be listed while receiving limited exposure. Another product may receive greater attention because it appears higher in search results, receives stronger ratings, has more reviews, or is featured in promotional placements.
Competitor monitoring can also reveal shifts in category strategy. If a competitor rapidly increases product coverage, launches multiple SKUs, or gains visibility across high-value searches, brands can identify these changes early.
The 2020–2026 period has demonstrated that digital shelf competition increasingly resembles traditional shelf competition, but with additional layers such as search ranking, paid placements, customer reviews, personalization, and dynamic content.
Share of voice and share of shelf are most useful when measured together. Share of voice generally focuses on how prominently a brand appears within a defined digital environment, while share of shelf focuses more on product representation or assortment presence.
E-commerce share of shelf and share of voice intelligence services can combine these dimensions into a broader competitive measurement framework.
| Metric | Primary Question | Example Application |
|---|---|---|
| Share of shelf | How much product representation does the brand have? | Assortment analysis |
| Share of voice | How visible is the brand? | Search visibility |
| Price position | How competitive is pricing? | Price benchmarking |
| Availability | Can consumers purchase the product? | Stock monitoring |
| Ratings | How do shoppers perceive products? | Reputation analysis |
| Reviews | What are customers discussing? | Sentiment insights |
| Promotions | How aggressively is the category promoted? | Campaign analysis |
From 2020 to 2026, these metrics increasingly became interconnected. A brand may have a large assortment but weak visibility. Another may have limited assortment but strong share of voice due to effective merchandising or advertising.
This is why benchmarking should avoid relying on a single metric. Combining multiple indicators can reveal the underlying reasons for performance differences.
For example, low share of voice combined with high share of shelf could indicate weak search visibility or content optimization. High share of voice but low share of shelf could indicate strong marketing performance with an opportunity to expand assortment.
The ability to connect these metrics allows brands to prioritize investments. Rather than increasing advertising spending automatically, a brand can first determine whether the underlying issue is assortment, availability, content, pricing, or search visibility.
Brands operating across multiple retailers often struggle to compare performance because each platform presents product information differently. A standardized data framework can solve this problem by normalizing product, visibility, pricing, and assortment information.
Amazon Walmart Target product visibility benchmarking and analytics provides a cross-platform framework for evaluating brand performance.
| Year | Benchmarking Priority | Strategic Use |
|---|---|---|
| 2020 | Product listing coverage | Digital expansion |
| 2021 | Assortment comparison | Catalog optimization |
| 2022 | Pricing comparison | Competitive positioning |
| 2023 | Search visibility | Discoverability |
| 2024 | Digital shelf quality | Merchandising |
| 2025 | Automated monitoring | Faster insights |
| 2026 | Integrated analytics | Cross-retailer strategy |
Standardization is critical because Amazon, Walmart, and Target may organize categories, product attributes, search results, and merchandising elements differently.
A consistent framework can map products to common categories and attributes. It can then compare brand presence, competitor presence, pricing, availability, and visibility using common definitions.
Historical benchmarking also enables brands to understand how their performance changes across retailers. For instance, a brand may have strong visibility on one platform but significantly weaker representation on another. Such differences can inform retailer-specific strategies.
The analysis can also support management reporting. Instead of presenting separate retailer reports, businesses can create a consolidated dashboard showing where the brand is gaining or losing digital visibility.
The final stage of benchmarking involves integrating retailer-specific datasets into a broader analytical environment. This helps brands understand not only where they stand but why their performance changes.
Walmart analytics can contribute valuable information about product representation, pricing, availability, category competition, and digital merchandising. When combined with the Share of Voice vs. Share of Shelf: Benchmark Report, these signals can support a more complete view of competitive positioning.
| Year | Intelligence Capability | Business Benefit |
|---|---|---|
| 2020 | Basic catalog monitoring | Product visibility |
| 2021 | Cross-retailer collection | Competitive comparison |
| 2022 | Price and promotion tracking | Commercial insights |
| 2023 | Search and visibility monitoring | Discoverability |
| 2024 | Digital shelf measurement | Merchandising optimization |
| 2025 | Automated benchmarking | Faster reporting |
| 2026 | Integrated intelligence | Strategic decision-making |
An integrated approach allows brands to investigate performance gaps systematically. Suppose a product has high share of shelf but low share of voice. The business can investigate search placement, product content, ratings, reviews, promotions, and advertising.
Similarly, strong share of voice but weak share of shelf may indicate that a brand has strong awareness but insufficient assortment coverage. Expanding the product portfolio or improving retailer distribution may therefore deliver greater value than simply increasing marketing investment.
This approach transforms benchmarking from a reporting exercise into a strategic decision-making tool.
Actowiz Metrics helps brands convert complex retail information into structured datasets designed for competitive analysis, digital merchandising, and market intelligence.
One of the key advantages is the ability to create customized monitoring frameworks across Amazon, Walmart, Target, marketplaces, retailer websites, and other digital commerce environments. Data can be collected around selected products, categories, competitors, keywords, locations, and time periods.
Target analytics can be incorporated alongside broader Share of Voice vs. Share of Shelf: Benchmark Report metrics to create a more complete understanding of digital retail performance.
Actowiz Metrics can support recurring collection of product information, pricing, promotions, availability, ratings, reviews, search visibility, assortment, and other accessible retail attributes. Data can then be normalized and organized into analytics-ready structures.
Historical datasets are particularly valuable because they allow brands to measure changes over time. Instead of asking only how much visibility a brand has today, businesses can determine whether its visibility is increasing, decreasing, or remaining stable.
The resulting insights can support e-commerce teams, brand managers, category managers, pricing teams, digital marketers, and business analysts.
Share of voice and share of shelf represent two complementary dimensions of digital retail performance. Share of shelf helps brands understand product representation, while share of voice provides insight into consumer-facing visibility. Evaluating both metrics together can reveal performance gaps that a single metric may overlook.
The evolution of digital commerce between 2020 and 2026 has made this comparison increasingly important. Retailers and marketplaces now contain larger assortments, more competitive search environments, dynamic pricing, promotions, reviews, and increasingly sophisticated digital merchandising.
For brands competing across Amazon, Walmart, and Target, standardized data collection and historical benchmarking can provide a clearer view of competitive positioning. Businesses can identify where products are underrepresented, where competitors are gaining visibility, and which digital shelf factors may be influencing performance.
E-commerce & D2C analytics can further connect retailer-level observations with broader brand performance, helping organizations build a more comprehensive digital commerce strategy. When combined with the Share of Voice vs. Share of Shelf: Benchmark Report, these insights can support better assortment decisions, visibility strategies, pricing initiatives, and competitive planning.
Ready to benchmark your brand's share of voice and share of shelf across Amazon, Walmart, and Target? Partner with Actowiz Metrics to build scalable retail intelligence datasets and turn digital shelf data into actionable competitive insights!
Expert blogs, research reports and infographics — practical, data-driven reading across e-commerce and quick-commerce.
Most fields are optional — the more you share, the better your sample.



.webp "infographics")
.webp "infographics")